Clear Reviews. Reliable Coverage. Total Peace of Mind.
NP Malpractice Insurance – Compare Coverage & Quotes
Explore essential tips for comparing NP malpractice insurance, ensuring you select the ideal coverage for your practice.

The moment a patient looks to you for care, a mix of pride and worry can follow. Many nurse practitioners feel that weight. That concern is real, and it is wise to plan.
Securing strong professional liability coverage protects your license and finances. Proliability has been the AANP-sponsored provider since 2008, and offers focused legal defense and tailored plans.
Premiums start at $862 for employed adult NPs and $1,035 for self-employed clinicians. These figures show how accessible a solid policy can be for new and experienced practitioners.
Understanding your options gives you practical peace of mind. With clear coverage limits and reliable defense services, you can focus on patient care and long-term practice stability.
Table of Contents
Understanding the Importance of NP Malpractice Insurance
Every clinical decision carries professional risk, and having clear coverage lets you focus on care. A tailored policy protects personal assets, supports a focused defense, and preserves your license if a claim arises.
Why Nurse Practitioners Need Protection
Employer policies often fall short. They may not cover all defense costs or individual reputational services. Individual professional liability insurance fills gaps and gives a team committed solely to your interests.
- Independent coverage protects against claims that involve your license or private assets.
- Healthcare settings are more litigious; dedicated protection reduces personal exposure.
- Knowing your limits and policy terms helps manage practice risk across states and care settings.
Protecting Your Professional License
Board inquiries can threaten the ability to practice and are costly to contest. A strong policy includes regulatory defense and support during investigations.
| Coverage Element | Why It Matters | Typical Limits |
|---|---|---|
| Legal defense | Funds attorneys and court costs | $100k–$1M+ |
| Regulatory board defense | Protects your license in investigations | $50k–$250k |
| Reputation support | Manages public and patient-facing fallout | Varies by policy |
Comparing Occurrence Versus Claims-Made Policies
How a claim is covered depends heavily on whether the policy is occurrence-based or claims-made.
Occurrence policies protect incidents that happen during the policy period, even if the claim is filed years later. This steady liability protection means your professional liability limits stay in place no matter when a claim appears.
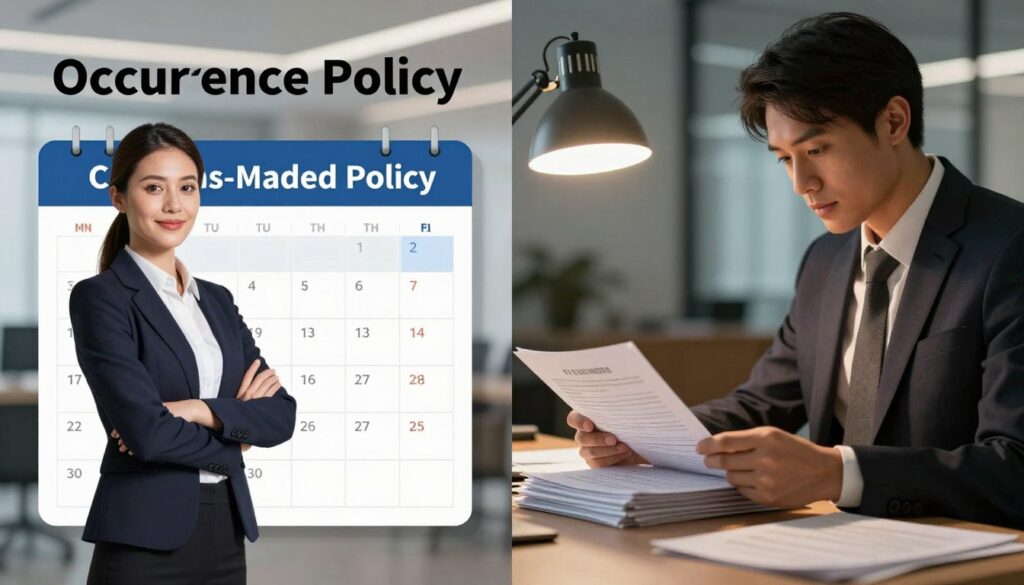
- Occurrence: Covers incidents during the policy period; no tail needed when you change employers.
- Claims-made: Also known as claims-made coverage; it only responds if the claim is reported while your policy is active.
- Tail coverage: Often required when leaving a claims-made plan and can be costly for some practitioners.
| Feature | Occurrence | Claims-Made |
|---|---|---|
| When covered | When incident occurs | When claim is filed |
| Need for tail | No | Yes, if you stop a policy |
| Stability of limits | Stable over time | Depends on active policy |
Many nurses and practitioners prefer occurrence-based plans for predictable defense and to avoid gaps when moving between facilities. For example, firms like Liberty Insurance Underwriters Inc. in Boston underwrite occurrence options that cover incidents during the policy period.
Evaluating Employer-Provided Coverage Gaps
A hospital or clinic policy often protects the organization first and the caregiver second.
Employer-provided plans can leave an individual nurse practitioner with limited options when a malpractice claim arises. Shared defense limits may be drained if several staff are named in the same lawsuit.
Identifying Limitations in Shared Defense
Common gaps include:
- Defense costs that erode policy limits rather than being paid in addition.
- No coverage for regulatory board proceedings or HIPAA penalties in many employer policies.
- Little control over settlement decisions that affect your reputation and license.
Gaps also appear during the policy period when you work outside your primary role, such as volunteering or moonlighting. Evaluating employer coverage is a necessary step for every practitioner.
| Issue | Employer Policy | Dedicated Policy |
|---|---|---|
| Defense control | Employer-led | Your counsel |
| Regulatory board defense | Often limited | Typically included |
| Limits under multi-defendant claim | Shared and depletable | Individual limits preserved |
Bottom line: Supplemental professional liability and liability insurance give you a dedicated legal advocate and protect personal limits so you can focus on patient care and practice stability.
Essential Features to Look for in Your Policy
Not all coverage is equal; the right features matter when a patient claim threatens a license or finances. Pick a plan that gives clear, usable protections at the moment you need them.
Legal Defense and Attorney Fees
Legal defense should be provided by counsel who represents you alone. Confirm that defense costs are paid in addition to your liability limits so settlements do not erode coverage.
HIPAA and Regulatory Board Coverage
Look for explicit HIPAA and board defense language. For example, Berxi offers up to $25,000 for HIPAA fines and another $25,000 for licensing board defense — protections many nurse practitioners value.
Reputation and Crisis Management
Rapid crisis management services can reduce reputational harm after a public claim. Also verify telehealth and evolving practice settings are included.
- Occurrence options avoid the need for tail coverage when you leave a job.
- Ensure regulatory board investigations are covered alongside malpractice defense.
- Confirm limits, defense funding, and services before you sign a policy.
| Feature | Why it matters | Typical offering |
|---|---|---|
| Defense costs | Preserves limits for settlements | Paid in addition |
| HIPAA & board | Protects license and fines | $25k each (example) |
| Crisis services | Manages public claims | On-call support |
Factors Influencing Your Insurance Costs
Several practical factors shape what you pay for professional protection each year.
Geography matters. Rates vary by state and local claim trends. Higher-risk regions often mean higher premiums.
Services you perform affect cost. Specialized procedures, telehealth, or extended hours raise exposure. Your claims history is also key; a clean record lowers renewal prices.
- Policy type — occurrence or claims-made — changes annual premiums.
- Chosen limits and working hours directly drive total costs.
- Buying directly from a carrier can cut middleman fees.
Berxi, part of Berkshire Hathaway Specialty Insurance with an A++ rating, often delivers competitive rates for many nurse practitioners. During the policy period, carriers track changes in practice and may adjust pricing if your role or risks shift.
| Factor | How it affects cost | Action to manage costs |
|---|---|---|
| Location (state) | Higher claim frequency raises rates | Compare state-specific quotes |
| Policy type | Occurrence vs claims-made alters premiums | Choose based on career plans |
| Claims history | Past claims increase renewals | Maintain records and risk controls |
| Limits & hours | Higher limits and longer hours cost more | Balance protection with budget |
How to Secure Your Professional Liability Coverage
A short, focused application is the fastest route to professional protection for a busy clinician.
Securing professional liability insurance can often be completed online in minutes. Applicants provide practice details such as state of licensure and the services they perform. This helps carriers match limits and add-ons to real risk.
Berxi offers live support Monday through Friday, 8:00am to 8:00pm ET, to guide you through quotes and questions. That assistance speeds approvals and clarifies policy period options like occurrence or claims-made.
- Provide accurate practice details to get correct limits and tailored coverage.
- Confirm board defense, HIPAA protection, and crisis services are included.
- Choose a policy that follows you across all 50 states for consistent liability protection.
| Step | What to Prepare | Why it Matters |
|---|---|---|
| Online application | Licensure state, services | Fast quote matching |
| Review limits | Per-claim and aggregate | Protects assets and reputation |
| Confirm services | Board defense, HIPAA | Full regulatory protection |
Having your own policy gives you dedicated legal defense and peace of mind. Whether new or experienced, obtaining independent coverage is a key step to protect your license, career, and financial future.
Conclusion
Protecting your practice starts with clear choices about coverage and defense.
Investing in your own malpractice insurance is the most effective way to safeguard a career and reputation. Understand the difference between occurrence and claims-made policies so you can pick what fits your path.
Prioritize plans that fund a dedicated legal defense and include regulatory support. Check limits often and update coverage as your scope of care changes.
Taking these steps gives you practical confidence. With the right protection in place, you can concentrate on delivering high-quality patient care every day.
FAQ
What is professional liability coverage for nurse practitioners?
Professional liability coverage protects nurse practitioners against claims alleging negligent acts, errors, or omissions in clinical services. It helps pay for defense costs, settlements, and judgments, and can include board defense and regulatory matters depending on the policy.
What’s the difference between occurrence and claims-made policies?
An occurrence policy covers incidents that happen during the policy period, even if a claim is filed later. A claims-made policy only covers claims reported while the policy is active; if you switch carriers or retire, you may need tail coverage to protect against later claims.
Do employer-provided policies fully protect individual clinicians?
Employer policies may cover clinicians for work performed for that employer, but they often have limits, shared defense arrangements, and exclusions. They may not cover moonlighting, independent practice, or licensing board investigations—so many practitioners carry their own policy for full protection.
What are common gaps in shared employer coverage?
Common gaps include inadequate limits for individual exposure, lack of coverage for non-employer work, no reimbursement for lost earnings during hearings, and conflicts of interest when the employer controls the defense. Reviewing policy language and carrying an excess or separate policy can close these gaps.
How important is legal defense and attorney fee coverage?
Very important. Defense costs can exceed settlement amounts. Look for policies that pay defense fees outside your liability limits, provide experienced healthcare defense counsel, and offer coverage for licensing board proceedings and subpoenas.
Will a policy cover HIPAA investigations or fines?
Some professional liability policies include coverage for HIPAA defense and regulatory actions, but coverage for fines and penalties varies by state and insurer. Confirm whether the policy covers investigation costs, civil fines, and administrative hearings related to privacy breaches.
Is reputation and crisis management included in standard policies?
Reputation and crisis management are not always standard. Many insurers offer add-ons or endorsements for media response, public relations, and patient notification costs. These services can be crucial after a serious claim to protect a clinician’s practice and license.
What factors influence premium costs for practitioner protection?
Premiums depend on specialty, claims history, practice setting, state law, annual revenue, limits chosen, and whether coverage is occurrence or claims-made. High-risk specialties and prior claims typically raise rates; strong risk management can reduce them.
How do limits and deductibles affect coverage decisions?
Higher limits provide more protection but cost more in premium. Choosing a higher deductible lowers premium but increases out-of-pocket exposure for small claims. Balance financial comfort with likely risk and employer requirements when selecting limits.
What is tail coverage and when is it needed?
Tail coverage extends reporting for claims-made policies after the policy ends. It’s needed when leaving a job, retiring, or switching to an occurrence policy to cover claims that arise from past care but are reported later.
How should a nurse practitioner evaluate insurers and policies?
Compare coverages, exclusions, claims-handling reputation, and whether defense costs reduce limits. Verify coverage for licensing board defense, telehealth services, and moonlighting. Read policy language and ask about endorsements relevant to your practice.
Can telehealth services affect coverage needs?
Yes. Telehealth can create jurisdictional and licensing exposures. Confirm the policy covers telehealth across state lines, includes appropriate limits, and addresses electronic record and privacy issues tied to remote care.
When should a practitioner buy an individual policy versus relying on employer coverage?
Buy an individual policy if you work multiple jobs, moonlight, run a private practice, or want protection independent of employer interests. An individual policy ensures control over defense and consistent coverage when employment changes.
How quickly can coverage start and what documentation is needed?
Many insurers offer same-day start after application and payment. Typical documentation includes state licensure, practice location, specialty, claims history, and employer information. Some carriers require a copy of your employment contract.
What should a practitioner do immediately after a patient files a claim?
Notify your insurer promptly, preserve records, avoid discussing the case publicly or admitting fault, and follow insurer guidance on documentation and communication. Quick reporting helps secure defense and limit exposure.
How do state laws affect professional liability coverage?
State laws govern damages caps, statute of limitations, licensing board authority, and whether certain fines are insurable. Policies must comply with state regulations, so check for state-specific exclusions or mandatory coverages.